Posts tagged: investments

Choosing the best retirement plan for a secure future

Financial retirementA financially secure future is what most of us are constantly working towards. We set a portion of our funds aside for a safe future, invest in 401(k) plans, set up IRA accounts and try investing in sound retirement plans based on part research, part hearsay. Choosing a safe investment vehicle is a matter most people lose their sleep over. Does a 401(k) plan carry interesting tax benefits? Does an IRA account effectively maximize your money? Are bonds a sounder investment option than stocks? These are some questions that might occur to you while trying to choose an optimum retirement plan, which keeps your future out of harm’s way.

The fundamental solution to a retirement plan problem is the understanding of tax benefits and returns that each investment plan offers. The 401(k) plan and the IRA (individual retirement account) are tax free investment options where you don’t have to pay taxes on the money invested or the interest unless you begin receiving benefits. As contributing to these accounts leads to a decrease in your taxable income, you pay lesser taxes overall. However, both methods are fundamentally different from each other and need careful research before they you take a decision.

While the 401(k) plan is set up by your employer, an IRA is an individual choice. The 401(k) plan will allocate similar distributions to employees, while an IRA leaves you with a lot of options as far as investment vehicles go. The 401(k) plan gives you the option of withdrawing money during an emergency; other than reducing your net taxable income. However, when you start to withdraw money from your account, the amount will be taxed as additional income. Also, there are penalties for premature withdrawal.

The IRA comes with its own pros and cons. You don’t need any help from a financial planner as the account is easy to set up. It also gives you a lot of freedom in choosing investment options like bonds, stocks or mutual funds. However, it imposes penalties on premature withdrawal and has a low contribution rate.

Through a 401(k) or an IRA account, you could invest your money in a number of things such as bonds, mutual funds, stocks, real estate and so on. Each profile has a unique risk to returns ratio that must be studied before choosing to invest in. The stock market has always been an enigmatic and unassailable investment option to most. With a high risk and an even higher reward associated with it, a stock portfolio could potentially take your investments to new heights. Bonds do not carry the high risk that stocks do, but neither do they offer promising returns on investment.

Choosing the best plan would require extensive research and an understanding of your financial requirements. Investing in both, IRA and a 410(k) could well be a sound diversification strategy, according to some professionals. Other new age IRA plans like investing in commercial real estate could also be the key to an assured future. Seek expert advice before going for any option available to you.
When retirement finally happens, a retirement plan could be your knight in shining armour. A careful approach towards choosing a sound plan will go a long way in ensuring financial security.

How Does Income Drawdown Work?

Income relatedIncome drawdown can provide a great way to keep you financially comfortable in later life. Here’s a look at how it works.

A Quick Look at Annuities

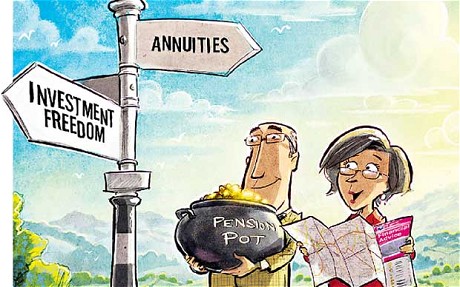
Income drawdown isn’t complicated, but it can be a little confusing if you’re only familiar with the annuity model of pensions. Annuities work like this: you make regular payments into your pension throughout your working life, and when you retire you use that money to purchase an annuity. An annuity is a financial product that guarantees you a fixed income until the day you die.

The problem with this model is that it may not provide for your needs. Annuity rates are dependent on market conditions, so when you go to retire, there is a chance that you may receive a poor rate. Although the payment is fixed, inflation means that it will decrease each year in real terms.

How Income Drawdown is Different

Instead of cashing in your pension on retirement day, income drawdown allows you to make regular cash withdrawals from your pension, within certain limits. You can vary the payments you receive according to your needs, and the money that you’ve invested will continue to grow.

To avail of income drawdown, you’ll need to choose a financial product such as a SIPP (Self-Invested Personal Pension) with drawdown functionality. SIPPs also offer a huge range of investment choices, giving you the opportunity to grow your fund even further.

What Kind of Payments Can I Get?

There are two types of payment available in an income drawdown pension:

  • Tax-free cash: 25% of your fund is available tax-free and can be withdrawn in instalments or taken as a one-off lump sum.
  • Income: Of the remaining 75%, you can withdraw money as and when you choose. These payments are subject to income tax, and their is a limit to how much you can withdraw each year. This limit is often referred to as the GAD Max, and you can withdraw up to your GAD Max each year. Whether you take this as a monthly payment or an annual lump sum is up to you.

How is My GAD Max Calculated

There are three factors in deciding your GAD limits. Your age and the value of the pension are both taken into consideration, with the intention that your income payments should be balanced in order to ensure a regular pension for the rest of your life. Gilt Yields, a figure issued each month by the Treasury, are also taken into account.

Your GAD Max is recalculated every three years, although in some circumstances you will be able to request a recalculation before then.

When Can I Start Taking Income Drawdown Payments?

You can begin drawing down form your pension at any time after the age of 55. You don’t need to have actually retired, although if you are still in employment then you’ll be liable to pay the same amount of income tax that you would pay on your normal salary.

Income drawdown payments can be reduced, increased (within GAD limits), stopped and restarted as you see fit.

Will I One Day Have to Purchase an Annuity?

No, you can continue to receive income payments for as long as you like. If you would like to purchase an annuity later on, you can do so with your remaining pension fund.

Are There Any Disadvantages to Income Drawdown?

Your pension payments are not guaranteed as they would be under an annuity arrangement. In order to keep receiving payments, you will need to have money in your pension and a bad investment choice may see your pension lose its value. This is why many income drawdown products are sold on an advice-only basis; it is recommend that you speak to a financial adviser before investing in such a product.

Motor Money Matters

Motor moneyWith the economy being stuck in a downturn and the rising cost of living (especially food prices), everybody seems to be cutting costs. Many people need to take out loans just to survive, but they need to be careful about where they go, because there are many places with high interest rates that do more harm than good.

The ideal situation is to stay debt free, but this is not always possible when school fees must be paid and fuel prices keep rising.

Some loans are harder to get then others

Buying a car is more difficult than previous years when, credit checks were not as strict and loans were not so difficult to obtain from financial institutions. These days, many people drive their cars to the end of the vehicle’s lifespan, as new cars are expensive.

Everybody needs money to survive, as well as insurance to protect the assets that they have against crime, damage and disaster. Fortunately, there are many insurers and financial institutions that offer products and loans that have the consumer’s best interests in mind. These companies are linked to a regulatory board that ensures fairness to the consumer or client.

Buying a car is never a simple process, and financing can be a nightmare to get if you don’t have the proper documents and forms. There are many types of contracts or loan types for vehicle finance that can confuse the prospective buyer.

Let’s uncomplicated it

The first step is to apply for financial backing from a bank or credit provider. It is recommended that the client gets as many quotes as possible to compare repayment plans and interest options. Apart from the practical considerations, such as the car’s make, model and features, the following financial questions should be asked:

From a finance point-of-view:

  • What size deposit can be put down, and how will it affect the monthly payments?
  • Does the dealership give discount for upfront deposits?
  • What is the interest rate on the payments?
  • What are the options regarding the payment period? Can the car be purchased over five or six years and what are the differences in installments?
  • Are payments fixed or will the amount vary with the interest rate?
  • Are there any hidden costs or increases in the installments?
  • Are there ways to pay off the car faster by paying extra during the months when the budget allows? What bank charges and administrative tasks, if any, are associated with these extra payments?

From an insurance point-of-view:

  • Is there a preferred insurer or can the buyer use any company to insure the vehicle?
  • Are there special deals with certain insurers that are linked to the car dealership?
  • Does the insurance company provide a courtesy car if there is a claim or theft?
  • How fast are claims settled?
  • How labour intensive is it to claim? Is it the vehicle owner’s responsibility to claim or will there be assistance from insurers?
  • What is the excess payment on insurance if a claim is made?
  • What are the details covered under insurance? Are the car’s contents covered or is it just the external body of the vehicle?

Buying a car is an expensive, life-changing decision. You can increase the value of your car to get your money’s worth, and extend its life by servicing it regularly and keeping it in optimal condition. Keep the tyres at the right pressure, complete regular checks, and keep the car tidy to obtain maximum usage from the car. The more reliable your car is, the better your chances of getting a good selling price when you want to move on.

5 Things To Know About Working In Sales Before You Apply

Career in sales1. Your Success Is Determined By Your Effort

The sales industry is heavily based on rewarding the salesperson’s effort with success. A salesperson that does not put in a hundred percent of their effort will sometimes make nothing at all if they are on a commission basis. On the other hand, sales staff that put in all of their time and effort can often make far beyond what their peers are making. Sales positions are not traditional positions even when they are salaried because bonuses and promotions are all merit-based. In many industries a person can become successful simply by showing up and doing their job adequately. Sales is not one of these industries.

2. Relationships Are Everything

In sales positions a good sales team member will need to have a good relationship with their boss, co-workers and clients. While this is true in most positions it is more vital in a sales position because everyone is working together as a team. Those who cannot have good relationships with their clients will not be able to sell as much but they also can’t neglect their relationship with their co-workers. Co-workers can make or break a salesperson’s career by sharing leads and generally making their life easier. Because of the high churn of the sales industry it’s also not uncommon to suddenly find a co-worker becoming a boss and this is where previous relationships will often pay off.

3. It’s Demanding

A sales job is usually not an ordinary 40 hour a week position. Most sales jobs require that the sales person work far beyond a regular work day and many skilled sales professionals will be doing their work and their research out of hours and often at home. Because sales positions are so high pressure and because a sales professional makes as much money as they work for it can be necessary for a sales professional to put in an extensive effort to become successful.

4. Determination Is Required

Sales positions offer a lot of room to grow but only for those who are determined and willing to be constantly pushing to move upwards. Sales is extremely competitive and that means that sales people need to be constantly improving their sales techniques and their numbers. Those who allow themselves to slip may find themselves losing a lot of traction in their professional life.

5. Confidence and Leadership Is Key

Sales is all about people skills and those who do not have the confidence to lead will not find themselves going very far. There are many seminars and programs available to help those who need to develop their personal and professional skills and many sales people will find these opportunities very rewarding. While client sales may be based on confidence, leadership is required to grow and advance in a sales career. A successful sales professional needs to be able to inspire those who work under them to be the best salespeople that they can be.

To check out some options, Randstad offer sales jobs for many companies that cover all interests.

Nicole is a recruitment agent and has been for the past 5 years. She aims to help her clients find jobs and guide them in the right direction. She started writing blogs to share her knowledge to others who are looking for general help and ideas to get them started on their career.

3 Things You Should Know About Before Investing In Diamonds

Investments in diamondsDiamonds are forever. We’ve all heard that statement before about these precious gems but now they are starting to be perceived in a much different manner: Growing wealth.

When most people think of investments, they usually think of the usual assets such as real estate, stocks, bonds and even gold. But for the first time, an exchange-traded fund (ETF) was debuted by PureFunds that focuses solely on diamonds and gemstones.

More diamond based funds are currently in the works, and it was only a matter of time. In October of last year, the U.S. consumer price index (CPI) marked a 12 percent year on year increase making a record high of 182.6 points.

These are definitely strong indicators of the value of investing in diamonds and gemstones with the trend likely to continue. However, as with all investments there, are risks involved. The following are three things that you should know before considering a diamond investment.

1. Educate yourself about the basics

Not all diamonds are created equal. Prices vary based on a number of factors including quality, color and cut. Before investing, there are certain requirements that need to be met first. The first is being aware of resale liquidity and having your investment confirmed by a specialist.

Establishing relationships with a diamond specialist will also help to give you access to dealer prices and will keep you involved in the entire process.

2. Invest in certain types of diamonds

It’s important to make investments that make the most sense for you.  Having a budget and doing some research can help you decide how much money you would like to invest, and where you would to invest it.  Never go into investing without a plan or without being knowledgeable about what you’re investing in.

Initial investments can start with those as recommended by the Rapaport Group: 1.01 to 1.49 carats, D-H color, IF-VS2 clarity and with Excellent cuts. These are simply guidelines as your investment objectives will vary.

3. Keep yourself protected

All diamond investments need to be thoroughly inspected for its quality and to ensure that you are getting what you are paying for. The Gemological Institute of America (GIA) is an authority for grading gems and includes detailed reports of all characteristics of the diamond including its color, clarity, cut and carat weight.

It’s important that your diamonds are always graded by the GIA. These measures ensure the quality of your investment. If you are serious about diversifying your investments with diamonds, be prepared to do your due diligence. You should always be 100% certain of what you are investing in.

Chuck Stevens is an avid blogger always looking to share his experiences and recommendations. He has been a financial advisor for over 10 years. You can follow him on Twitter @chuckstevens12.